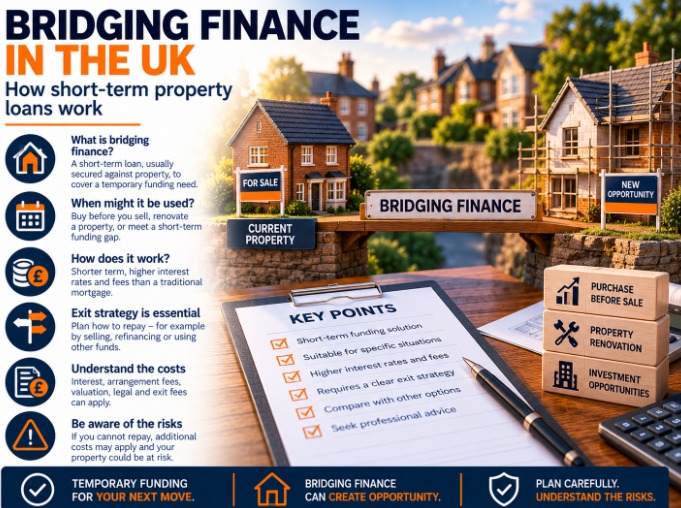

Property transactions do not always follow a straightforward timeline. A buyer may need to complete a purchase before selling an existing property, an investor may want to acquire a property that requires renovation, or a homeowner may face a short-term funding gap.
In certain situations, bridging finance can provide temporary funding while the borrower arranges a longer-term solution. However, bridging loans can be expensive and carry significant risks. They should be considered carefully rather than treated as a convenient alternative to a standard mortgage.
Understanding how bridging finance works, what lenders assess, and how the loan will be repaid is essential before proceeding.
What Is Bridging Finance?
Bridging finance is a form of short-term borrowing commonly secured against property. It is designed to cover a temporary funding need, with repayment expected from a defined source within an agreed period.
The exact terms depend on the lender, the security offered, the borrower’s circumstances, and the purpose of the loan.
Unlike a traditional residential mortgage, which may run for decades, a bridging loan usually has a much shorter term. Interest rates and fees can be higher than those associated with conventional mortgages.
Bridging finance may be arranged for residential or commercial property purposes, but the regulatory treatment can differ depending on the borrower, property, and intended use.
When Might a Bridging Loan Be Considered?
One possible use is buying a new property before completing the sale of an existing home. If the timing of the two transactions does not align, a borrower may need temporary funds to complete the purchase.
Another example involves purchasing a property that requires substantial work before it meets the requirements of a conventional mortgage broker. A bridging loan might provide temporary funding while the borrower completes the work and arranges longer-term finance.
Property investors may also consider bridging finance when a transaction requires a fast completion or when the property is not immediately suitable for a standard mortgage.
These examples do not mean that bridging finance is always appropriate. Borrowers should compare alternative arrangements and confirm that the expected repayment route is realistic.
How Do Bridging Loans Work?
The lender assesses the property offered as security, the amount requested, the borrower’s financial circumstances, and the proposed repayment plan.
The loan may be structured with different approaches to interest payments. Depending on the product, interest may be paid monthly, retained or deducted in another way, or added to the amount due at the end. The exact arrangement must be understood before signing the agreement.
Some bridging loans are described as open or closed.
A closed bridging loan usually has a defined repayment date linked to a clear event, such as a property sale with an established completion timetable.
An open bridging loan may not have a fixed repayment date in the same way, although it will still have contractual terms and a maximum duration. The absence of a confirmed completion date can increase uncertainty.
Neither structure removes the need for a credible exit strategy.
Understanding the Exit Strategy
The exit strategy is the plan for repaying the bridging loan.
Possible strategies may include selling a property, refinancing onto a longer-term mortgage, or using other funds that are expected to become available.
The exit must be realistic in terms of timing, affordability, and lender requirements. If the plan depends on refinancing, remember that a future lender will conduct its own assessment. Approval is not guaranteed.
If the plan depends on selling a property, consider the possibility that the sale may take longer than expected or that the final price may be lower than anticipated.
A contingency plan is important. Without one, a delay could lead to additional interest, fees, or difficulties repaying the loan when due.
Costs and Fees to Consider
Bridging finance may involve several costs beyond the headline interest rate.
These can include arrangement fees, valuation fees, legal costs, broker fees, exit fees, and charges associated with extending or repaying the loan early. The amount and structure vary by product.
If interest is added to the loan balance, the amount owed can increase over time. Borrowers should understand whether interest is calculated on the original principal or on a balance that includes previously added interest, according to the contract.
Ask for a clear breakdown of the total amount payable under realistic scenarios. Consider what the cost would be if the property sale or refinancing took longer than planned.
Comparing the annual interest rate alone may not provide a complete picture of the total cost of short-term borrowing.
What Do Lenders Assess?
Lenders may examine the property value, the loan-to-value ratio, the intended use of the funds, the borrower’s financial position, and the repayment plan.
They may also consider the property’s condition, the experience of the borrower where relevant, and the complexity of the transaction.
If the loan is intended to fund renovations, establish what work is required, how much it is expected to cost, and whether the proposed budget is realistic.
The lender may require a valuation and legal checks before funds can be released. A short expected completion timetable does not mean that due diligence can be ignored.
Bridging Finance Versus a Traditional Mortgage
A traditional mortgage is generally designed for longer-term property borrowing and may offer lower interest rates than bridging finance.
However, conventional mortgage applications can involve more extensive affordability assessments and may not suit every property or transaction.
Bridging finance may provide greater flexibility in certain circumstances, but that flexibility comes with costs and repayment pressure.
The two products should not be compared only by the speed of obtaining funds. Consider the overall cost, contractual obligations, suitability, and consequences if the intended exit fails.
Important Risks to Understand
The principal risk is being unable to repay the loan when it falls due.
If a property sale is delayed, refinancing is refused, or the borrower cannot obtain the expected funds, the loan may remain outstanding beyond the planned period. Additional interest and charges may apply, and the lender may take enforcement action in accordance with the agreement and applicable law.
Because bridging finance is often secured against property, borrowers could ultimately risk losing the property if they cannot meet their obligations.
Avoid borrowing on the assumption that property prices will rise or that a refinancing application will automatically succeed.
Seek Professional Guidance
Bridging finance can be complex, especially when a transaction involves multiple properties, renovation work, or uncertain sale dates.
Prestige Mortgage Solutions Ltd may be a point of contact for people exploring property finance options. Before using any firm, confirm its relevant regulatory permissions, fees, service scope, and experience with the specific type of finance required.
Depending on the transaction, independent legal, tax, valuation, and financial advice may also be appropriate.
Final Thoughts
Bridging finance can help address a short-term funding gap, but it should be supported by a realistic repayment plan and a clear understanding of all costs.
Before proceeding, compare alternatives, test the exit strategy under less favourable conditions, and consider what will happen if the transaction takes longer than expected.
This article provides general information only and is not personalised financial, mortgage, investment, legal, or tax advice. Bridging finance can carry substantial costs and risks, and availability depends on lender criteria and individual circumstances.