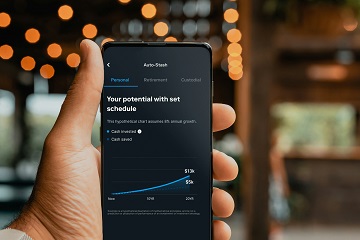

Introduction to Personal Finance in a Digital Era
Personal finance is a crucial aspect of financial literacy that encompasses various elements including budgeting, saving, investing, and debt management. In an increasingly complex financial landscape, understanding these components is essential for individuals aiming to achieve financial stability and security. Budgeting, for instance, allows individuals to track their income and expenses, ensuring that they live within their means while planning for future financial goals. Saving is equally important, as it enables individuals to set aside funds for emergencies, large purchases, or retirement.
Investing, on the other hand, involves allocating resources into financial assets with the expectation of generating income or profit over time. It is vital for wealth accumulation and often necessitates a long-term perspective. Lastly, effective debt management is fundamental in maintaining overall financial health, as it ensures that obligations are met without placing undue strain on personal finances.
With the advent of the digital economy, the landscape of personal finance has undergone significant transformation. Today, technology provides access to various tools that facilitate better financial management. From budgeting apps to online investment platforms, individuals are now better equipped to handle their personal finances with greater efficiency and transparency. Furthermore, digital payment systems and financial technologies have simplified the processes of saving and spending, allowing for seamless transactions that save both time and effort.
As reliance on technology to manage personal finances continues to grow, it is imperative to explore how these digital innovations are reshaping traditional financial practices. This discussion will delve into the evolving nature of personal finance within the context of a digital economy, highlighting the opportunities and challenges it presents to individuals striving for financial well-being.
The Rise of FinTech: Revolutionizing Personal Finance
The digital economy has witnessed a remarkable transformation in recent years, largely fueled by the rise of financial technology, commonly referred to as fintech. This sector encompasses a wide array of innovative solutions that have redefined how individuals manage their personal finances. Fintech companies leverage technology to provide efficient and user-friendly services that enhance financial convenience and accessibility.
One of the notable advancements in this space is the emergence of digital wallets. These tools enable users to make seamless transactions, store payment information securely, and even manage cryptocurrency. Digital wallets not only facilitate quick purchases but also promote better budgeting by providing users with real-time insights into their spending habits. As a result, consumers can manage their finances more effectively, minimizing overspending and encouraging savings.
Another significant player in the fintech arena is the robo-advisor platform, which has democratized investment management. Traditionally, investing required considerable capital and expertise, often placing it out of reach for everyday individuals. Robo-advisors employ algorithms to provide automated, algorithm-driven financial planning services with little to no human intervention. This innovation allows users to access tailored investment portfolios at a fraction of the cost of traditional financial advisors, empowering them to grow their wealth and gain confidence in their investment decisions.
Moreover, peer-to-peer lending platforms have emerged as an alternative to conventional banks for obtaining loans. By connecting borrowers directly with individual lenders, these platforms reduce reliance on traditional banking systems and offer competitive interest rates for both parties. This model not only simplifies the borrowing process but also promotes financial inclusion, allowing individuals with limited access to credit to secure necessary funds.
In summary, the rise of fintech is revolutionizing personal finance management by introducing transformative solutions such as digital wallets, robo-advisors, and peer-to-peer lending platforms. These advancements are reshaping traditional finance practices, making them more efficient, accessible, and user-centric, thus signaling a new era in personal finance management.
Digital Currency: Cryptocurrencies and Beyond
In recent years, the rise of digital currencies has significantly changed the landscape of personal finance. Notable examples include Bitcoin and Ethereum, both of which have made substantial impacts on how individuals approach investing and spending in today’s digital economy. These cryptocurrencies offer unique features and benefits that appeal to a growing number of consumers and investors alike.
Cryptocurrencies operate on decentralized networks, providing users with enhanced privacy and security compared to traditional banking systems. Transactions made with digital currencies are typically faster and incur lower fees, making them attractive options for everyday use in personal finance management. Furthermore, the increasing adoption of blockchain technology has paved the way for additional cryptocurrencies and digital assets, evolving the range of options available to users.
The integration of these digital currencies into personal finance strategies presents both opportunities and challenges. For early adopters, investing in cryptocurrencies can yield significant returns, but the volatility associated with these assets poses inherent risks. Investors must navigate fluctuating market conditions while also considering the broader regulatory landscape that is gradually taking shape around digital currencies. As governments and financial institutions begin to introduce frameworks for managing these assets, the future of cryptocurrencies will be heavily influenced by regulatory developments.
Moreover, the emergence of digital currencies extends beyond just cryptocurrencies. Stablecoins, which are pegged to traditional fiat currencies, provide a more stable investment vehicle while still leveraging the benefits of blockchain technology. Additionally, the concept of Central Bank Digital Currencies (CBDCs) is gaining traction, with various nations exploring the prospect of governmental digital currencies. These developments further underscore the significance of digital currencies in shaping personal finance in a rapidly evolving economic environment.
The Role of Artificial Intelligence in Personal Finance
In recent years, artificial intelligence (AI) has emerged as a transformative force in the domain of personal finance. By leveraging advanced algorithms and machine learning, AI applications are enabling individuals to manage their finances more effectively than ever before. This section will explore how AI is reshaping various aspects of personal finance, including budgeting, investment strategies, and overall financial planning.
One of the most significant contributions of AI in personal finance is its ability to enhance budgeting through automation. AI-driven budgeting applications can analyze users’ spending habits and automatically categorize expenses, thereby providing meaningful insights that can help individuals curb unnecessary spending. Through real-time analytics, these applications suggest personalized adjustments, allowing users to stick to their financial goals with greater ease.
Investment recommendations also see substantial improvements thanks to AI. With the vast amount of financial data available today, AI can assess market trends and perform analyses at a speed and accuracy unattainable by humans alone. By employing advanced predictive models, these systems can forecast potential investment opportunities tailored to individual risk appetites, ultimately fostering better financial decisions among users.
Furthermore, AI enhances financial planning by offering personalized advice based on individual financial circumstances. This includes evaluating factors such as income, expenses, debts, and long-term goals. By utilizing natural language processing, AI can facilitate interactions with users, providing them with nuanced insights to improve their overall financial health.
However, while the benefits of AI in personal finance are considerable, potential concerns regarding data privacy and security remain paramount. As these AI tools require sensitive financial data to function effectively, users must be vigilant about protecting their personal information. Ensuring robust security measures is essential as we integrate AI into our financial ecosystems.
The Increasing Importance of Financial Education
In today’s rapidly evolving digital economy, the significance of financial education has never been more pronounced. As technology continues to reshape the way we manage money, individuals are presented with a variety of digital tools and platforms designed to facilitate financial decision-making. However, the effectiveness of these tools is contingent upon a fundamental understanding of personal finance principles and digital literacy. Without adequate financial education, users may struggle to leverage these innovations effectively, leading to mismanagement of their resources.
The growing prominence of online banking, investment apps, and cryptocurrency platforms underscores the urgency of enhancing financial literacy among the public. These digital finance solutions offer unprecedented access to financial services; yet, they also introduce a layer of complexity that could overwhelm those lacking the necessary knowledge. For instance, understanding how to navigate the stock market through an online platform requires more than just downloading an app; it necessitates a comprehension of market trends, investment risks, and regulatory frameworks.
Moreover, the introduction of digital payment systems and alternative currencies has led to a paradigm shift in financial transactions. As consumers increasingly engage with these technologies, it is crucial that they cultivate a strong foundation in finance to avoid pitfalls such as fraud or poor investment decisions. Educational initiatives aimed at improving financial literacy should therefore prioritize the integration of practical skills and theoretical knowledge, equipping individuals not just to utilize financial tools, but also to understand the implications of these financial choices in a broader economic context.
Challenges and Risks in the Digital Finance Landscape
The emergence of digital finance has transformed the way individuals and businesses manage their financial assets. However, this shift is not without its challenges and risks, which must be addressed to ensure a safe financial environment. Among the most pressing concerns are cybersecurity threats, data breaches, and the inherent volatility of digital currencies.
Cybersecurity threats are perhaps the most significant issue facing digital finance today. With the increasing reliance on online platforms for banking, investing, and other financial transactions, cybercriminals are constantly devising new strategies to exploit vulnerabilities. Ransomware attacks, phishing schemes, and identity theft can compromise sensitive financial information, leading to catastrophic consequences for both individuals and institutions. As such, users must practice vigilance and invest in secure, well-established financial platforms that prioritize data protection.
Data breaches represent another substantial risk in the realm of digital finance. Malicious actors may target financial institutions and payment systems, seeking to access confidential information and potentially causing financial ruin for affected clients. The ramifications of such breaches extend beyond immediate financial loss; they can erode trust in digital financial systems, deterring potential users from embracing these innovative solutions.
Furthermore, the volatility of digital currencies adds an additional layer of risk. The values of cryptocurrencies can fluctuate dramatically within short periods, which can lead to instability in personal finances for users who invest heavily in them. Prospective investors must carefully consider their risk tolerance and familiarize themselves with market trends before engaging with these currencies.
In conclusion, while digital finance offers numerous advantages, users must remain aware of the associated challenges and risks. By taking precautionary measures and staying informed, individuals can better navigate the complexities of the digital finance landscape, ensuring their financial well-being in an increasingly interconnected world.
The Future of Banking and Traditional Financial Institutions
As the landscape of personal finance transforms within the digital economy, traditional financial institutions are compelled to evolve. Banking institutions are recognizing the necessity to adapt, driven largely by the rapid advancements in fintech solutions that offer innovative services, greater convenience, and a more user-friendly experience for consumers. This adaptation takes various forms, such as enhancing online banking services, developing mobile applications, and embracing digital account management systems.
Online banking services have become indispensable as customers increasingly prioritize flexibility and accessibility. Traditional banks are investing in robust digital platforms that allow customers to perform a range of transactions from the comfort of their homes. These services include fund transfers, bill payments, and account monitoring, all of which have streamlined personal finance management. The goal is to create a seamless user experience that rivals that of digital-only banks.
Mobile applications are another cornerstone in the banks’ adaptation strategy. With the growing prevalence of smartphones, banks are implementing intuitive mobile banking apps that enable users to access their accounts instantly, monitor expenditures, and receive real-time alerts. This shift not only enhances customer satisfaction but also facilitates financial literacy by providing users with tools to manage their finances more effectively.
Furthermore, digital account management is revolutionizing how customers interact with their finances. Personalized dashboards, automated budgeting tools, and intelligent spending analysis are features being integrated into banking applications, helping users make informed decisions. This emphasis on user-centric design is vital for traditional banks aiming to retain their customer base in an increasingly competitive environment dominated by fintech innovations.
In conclusion, as traditional financial institutions continue to adapt to the digital economy, their focus on innovation will determine their ability to compete effectively. By leveraging online services, mobile technologies, and advanced account management solutions, banks are striving to offer a comprehensive financial experience that meets the evolving needs of consumers in this new digital age.
Impact of Regulatory Changes on Personal Finance
The landscape of personal finance is undergoing significant transformations influenced by regulatory changes associated with financial technology (fintech) and digital currencies. As the adoption of these digital solutions expands, so too does the necessity for robust regulations that ensure consumer protection, promote innovation, and maintain market integrity. These regulatory frameworks can significantly impact how individuals manage their personal finances.
Currently, regulations are evolving rapidly, with governments around the world introducing new policies to govern the myriad of fintech services available today. One of the most notable areas of focus is data protection. With the increasing digitization of personal finance, consumers find themselves entrusting sensitive financial information to digital platforms. Consequently, data privacy laws, such as the General Data Protection Regulation (GDPR) in the European Union, have set stringent requirements for how financial platforms handle personal data. These regulations aim to empower consumers by providing them with greater control over their information, thereby fostering trust in digital financial services.
Moreover, compliance standards for financial institutions and fintech organizations are also being adjusted to accommodate the rise of cryptocurrency and blockchain technologies. Regulatory bodies are tightening regulations to ensure these entities adhere to anti-money laundering (AML) and know-your-customer (KYC) practices, which require users to verify their identities. This is particularly relevant for individuals engaging in transactions via digital currencies, as regulatory clarity can significantly influence consumer adoption and investment choices.
As we look ahead, it is essential to anticipate future regulatory developments and their potential impact on personal finance management. Financial technology is expected to continue evolving rapidly, and proactive engagement with regulatory bodies will be vital for consumers and fintech organizations alike. By staying informed about these changes, individuals can better navigate their financial futures in an increasingly digital economy.
Conclusion: Preparing for the Future of Personal Finance
As we navigate the increasingly complex digital economy, the significance of personal finance has never been clearer. The tools and technologies designed to enhance our financial experiences are evolving rapidly, offering individuals unprecedented opportunities to manage and grow their finances. To effectively harness these tools, understanding the changing landscape of personal finance becomes imperative.
Firstly, leveraging technology, such as budgeting apps and digital investment platforms, can significantly improve financial literacy. These tools provide immediate feedback on spending habits and investment performance, allowing users to make informed decisions. As we embrace these innovations, it is important to remain vigilant about data privacy and security to protect our sensitive financial information from potential threats.
Furthermore, continuous education in financial management is essential. Individuals should seek to deepen their knowledge about emerging financial trends, from cryptocurrencies to sustainable investing. This proactive approach will empower them to capitalize on new opportunities while understanding associated risks. Additionally, staying informed about regulatory changes that impact personal finance can help individuals navigate the evolving legal framework governing these digital tools.
Networking with financial advisors and participating in online communities can also offer valuable insights and support. Engaging with others who are adept in personal finance enriches understanding and exposes individuals to diverse strategies for financial growth.
In summary, preparing for the future of personal finance requires a proactive and informed approach. By embracing digital tools, continuously educating oneself, and building a supportive network, individuals can significantly enhance their financial well-being in this digital age. As we move forward, adapting to the transformation of personal finance tools will be key in thriving within the digital economy.